Category: Market Action

Market Action

September 25, 2026

Bond market excitement continued:

US longer-dated Treasury yields rose on Friday, extending their recent sharp move higher after more upbeat economic data reinforced concerns about inflation.

The 30-year US bond yield hit a fresh 22-year high and the benchmark ⁠10-year yield ​reached a fresh 19-year high.

Yields have jumped recently on persistent worries about higher inflation.

New orders for key US manufactured capital goods increased more than expected in August and the previous month’s figures were revised sharply higher, signaling another quarter of robust growth in business spending on equipment ​amid an AI buildout.
…
The bullish data has driven up expectations for another interest-rate increase by the Federal Reserve. Traders now see a more than 64% chance of another hike when the US central bank next meets in October, according to CME Group’s FedWatch Tool. That expectation was around ‌55% a ​week ago.
…
The yield on the 30-year bond was last up 2.4 basis points at 5.486%. It reached 5.5319%, the ‌highest since 2004.

The yield on the benchmark US 10-year Treasury note was last up 0.3 basis point at 5.165%. ​It earlier reached 5.2297%, the highest since 2007.

A closely watched part of the US Treasury yield curve measuring the gap between yields on two- and 10-year Treasury notes, seen as an indicator of economic expectations, was at 30.3 basis points.

The two-year US Treasury yield, which ​typically moves in step with interest rate expectations for the Fed, was down 3.5 basis points at 4.86%.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.8657 % 2,762.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.8657 % 5,202.7
Floater 5.23 % 5.31 % 29,502 15.03 3 -0.8657 % 2,998.3
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2389 % 3,620.5
SplitShare 4.67 % 4.81 % 50,052 2.51 4 -0.2389 % 4,323.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2389 % 3,373.5
Perpetual-Premium 5.81 % 5.85 % 66,713 14.10 9 -0.6553 % 2,987.7
Perpetual-Discount 5.82 % 5.90 % 42,146 14.04 21 -0.7478 % 3,250.0
FixedReset Disc 5.67 % 6.23 % 79,504 13.52 21 -0.5567 % 3,361.7
Insurance Straight 5.70 % 5.79 % 57,609 14.22 19 -0.2397 % 3,159.2
FloatingReset 0.00 % 0.00 % 0 0.00 0 -0.5567 % 4,104.7
FixedReset Prem 5.98 % 4.57 % 77,177 2.10 27 -0.2068 % 2,640.5
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -0.5567 % 3,436.3
FixedReset Ins Non 5.23 % 5.45 % 48,922 1.86 14 0.0913 % 3,263.0
Performance Highlights
Issue Index Change Notes
BN.PR.T FixedReset Disc -3.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 22.31
Evaluated at bid price : 23.10
Bid-YTW : 6.27 %
MFC.PR.L FixedReset Ins Non -2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 23.28
Evaluated at bid price : 24.60
Bid-YTW : 5.79 %
ENB.PR.D FixedReset Disc -2.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 22.59
Evaluated at bid price : 23.01
Bid-YTW : 6.44 %
BN.PF.A FixedReset Prem -2.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 23.61
Evaluated at bid price : 25.07
Bid-YTW : 6.45 %
BN.PR.K Floater -1.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 14.51
Evaluated at bid price : 14.51
Bid-YTW : 5.40 %
PWF.PR.Z Perpetual-Discount -1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 21.63
Evaluated at bid price : 21.88
Bid-YTW : 5.98 %
POW.PR.A Perpetual-Discount -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 23.49
Evaluated at bid price : 23.76
Bid-YTW : 5.90 %
MFC.PR.C Insurance Straight -1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 20.40
Evaluated at bid price : 20.40
Bid-YTW : 5.56 %
MFC.PR.F FixedReset Ins Non -1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 21.41
Evaluated at bid price : 21.68
Bid-YTW : 5.64 %
CU.PR.J Perpetual-Discount -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 20.56
Evaluated at bid price : 20.56
Bid-YTW : 5.84 %
BN.PF.G FixedReset Prem -1.42 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2030-07-01
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 5.67 %
POW.PR.G Perpetual-Discount -1.37 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 23.48
Evaluated at bid price : 23.75
Bid-YTW : 5.90 %
BN.PR.X FixedReset Disc -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 21.44
Evaluated at bid price : 21.75
Bid-YTW : 6.13 %
PWF.PR.P FixedReset Disc -1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 21.59
Evaluated at bid price : 21.90
Bid-YTW : 5.79 %
BN.PF.D Perpetual-Discount -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 20.15
Evaluated at bid price : 20.15
Bid-YTW : 6.12 %
CU.PR.K Perpetual-Premium -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 23.84
Evaluated at bid price : 24.20
Bid-YTW : 5.84 %
SLF.PR.D Insurance Straight -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 5.50 %
POW.PR.B Perpetual-Discount -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 22.71
Evaluated at bid price : 22.95
Bid-YTW : 5.83 %
PWF.PR.G Perpetual-Premium -1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 24.68
Evaluated at bid price : 25.00
Bid-YTW : 5.99 %
GWO.PR.M Insurance Straight -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 24.43
Evaluated at bid price : 24.67
Bid-YTW : 5.90 %
POW.PR.H Perpetual-Premium -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 24.05
Evaluated at bid price : 24.43
Bid-YTW : 5.88 %
PWF.PR.R Perpetual-Discount -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 23.32
Evaluated at bid price : 23.60
Bid-YTW : 5.92 %
POW.PR.D Perpetual-Discount -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 21.34
Evaluated at bid price : 21.61
Bid-YTW : 5.79 %
GWO.PR.Y Insurance Straight 1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 19.75
Evaluated at bid price : 19.75
Bid-YTW : 5.73 %
MFC.PR.B Insurance Straight 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 21.01
Evaluated at bid price : 21.01
Bid-YTW : 5.58 %
SLF.PR.E Insurance Straight 1.99 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 5.52 %
FTS.PR.J Perpetual-Discount 2.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 5.65 %
IFC.PR.G FixedReset Ins Non 6.25 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.50
Bid-YTW : 4.80 %
Volume Highlights
Issue Index Shares
Traded
Notes
BN.PF.A FixedReset Prem 123,590 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 23.61
Evaluated at bid price : 25.07
Bid-YTW : 6.45 %
CU.PR.C FixedReset Disc 102,700 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.12
Bid-YTW : 5.04 %
MFC.PR.I FixedReset Ins Non 58,900 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-09-19
Maturity Price : 25.00
Evaluated at bid price : 25.36
Bid-YTW : 4.60 %
IFC.PR.C FixedReset Ins Non 35,600 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2026-10-30
Maturity Price : 25.00
Evaluated at bid price : 24.99
Bid-YTW : 5.81 %
GWO.PR.L Insurance Straight 27,919 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 23.95
Evaluated at bid price : 24.20
Bid-YTW : 5.86 %
PWF.PR.L Perpetual-Discount 25,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 21.75
Evaluated at bid price : 22.00
Bid-YTW : 5.89 %
There were 7 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
POW.PR.B Perpetual-Discount Quote: 22.95 – 24.13
Spot Rate : 1.1800
Average : 0.7271

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 22.71
Evaluated at bid price : 22.95
Bid-YTW : 5.83 %

BN.PR.Z FixedReset Disc Quote: 23.50 – 25.38
Spot Rate : 1.8800
Average : 1.5019

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 23.02
Evaluated at bid price : 23.50
Bid-YTW : 6.91 %

BN.PR.T FixedReset Disc Quote: 23.10 – 24.19
Spot Rate : 1.0900
Average : 0.7433

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 22.31
Evaluated at bid price : 23.10
Bid-YTW : 6.27 %

MFC.PR.L FixedReset Ins Non Quote: 24.60 – 25.60
Spot Rate : 1.0000
Average : 0.6628

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 23.28
Evaluated at bid price : 24.60
Bid-YTW : 5.79 %

IFC.PR.E Insurance Straight Quote: 22.60 – 23.75
Spot Rate : 1.1500
Average : 0.8229

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 22.33
Evaluated at bid price : 22.60
Bid-YTW : 5.77 %

BN.PF.A FixedReset Prem Quote: 25.07 – 26.14
Spot Rate : 1.0700
Average : 0.7585

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-25
Maturity Price : 23.61
Evaluated at bid price : 25.07
Bid-YTW : 6.45 %

Market Action

September 24, 2026

The TXPR price index was down 52bp today. Volume was 707,980, near the median of the second-highest volume of the past 20 trading days.

CPD was down 71bp to 13.95, on volume of 136,110 (consolidated: 332,330), highest of the past 20 trading days.

ZPR was down 31bp today on volume of 139,470 (consolidated: 423,470) above the median of the past 20 trading days.

There’s some hawkish talk from Fed governors:

The U.S. central bank will likely need to raise interest rates again to curb unacceptably high inflation, two Federal Reserve policy-makers said on Thursday.

“Returning inflation to 2 per cent is a top priority, and I will support the policy path that gets us there while carefully weighing risks to the labor market along the way,” Philadelphia Fed President Anna Paulson told a conference at her regional bank.

Paulson, a voting member of the central bank’s rate-setting Federal Open Market Committee, described inflation as “stubbornly elevated” and said “if conditions evolve as I expect, some modest further tightening may be warranted.”

Speaking in London, New York Fed President John Williams also suggested tighter monetary policy is coming. Citing Fed policy maker projections released last week that penciled in a rate increase, he said “it’s likely that another rate hike may be appropriate by the end of the year. That seems to me a reasonable way of thinking about it.”

Paulson and Williams spoke just over a week after the Fed raised its benchmark interest rate by a quarter of a percentage point, to the 3.75-to-4.00-per-cent range, in an effort to curb high inflation that threatens to undermine public confidence in the central bank’s ability to reach the 2-per-cent target.

The bond market continued its weakness:

US and Iranian leaders exchanged barbs this week at the UN General Assembly. Brent crude prices rose ​over 3% to nearly US$107 per barrel after a Houthi missile attack on ‌Saudi Arabia revived fears of supply disruptions.
…
The U.S. 30-year Treasury bond yield reached its highest since 2004. The yield on the benchmark U.S. 10-year Treasury climbed to 5.21% by late afternoon, up 10 basis points and its highest since early this century. The Canadian 10-year yield was up about 5 basis points to near 4%, its highest since 2023.
…
The S&P 500 declined 0.02% to end the session at 7,704.13 points. The Nasdaq edged up 0.01% to 26,939.37 points, while the Dow Jones Industrial Average declined 0.31% to 51,349.98 points.

The ​TSX ended down 44.97 points, or 0.1%, at 35,706.46, its lowest closing level since September 16.

The Canada five-year finished the day at 3.72%.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.4200 % 2,786.9
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.4200 % 5,248.1
Floater 5.19 % 5.29 % 27,571 15.06 3 -0.4200 % 3,024.5
OpRet 0.00 % 0.00 % 0 0.00 0 0.0299 % 3,629.2
SplitShare 4.65 % 4.55 % 51,901 2.51 4 0.0299 % 4,334.0
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0299 % 3,381.6
Perpetual-Premium 5.77 % 5.79 % 65,557 14.20 9 -0.6953 % 3,007.4
Perpetual-Discount 5.77 % 5.84 % 41,217 14.09 21 -0.7809 % 3,274.5
FixedReset Disc 5.63 % 6.21 % 82,769 13.54 21 -0.1240 % 3,380.5
Insurance Straight 5.68 % 5.77 % 54,983 14.27 19 -0.5008 % 3,166.8
FloatingReset 0.00 % 0.00 % 0 0.00 0 -0.1240 % 4,127.6
FixedReset Prem 5.97 % 4.81 % 77,959 2.01 27 -0.1807 % 2,646.0
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -0.1240 % 3,455.6
FixedReset Ins Non 5.24 % 5.40 % 49,615 2.52 14 0.8491 % 3,260.0
Performance Highlights
Issue Index Change Notes
BN.PR.Z FixedReset Disc -7.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 23.02
Evaluated at bid price : 23.50
Bid-YTW : 6.91 %
MFC.PR.B Insurance Straight -4.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 20.74
Evaluated at bid price : 20.74
Bid-YTW : 5.65 %
FTS.PR.J Perpetual-Discount -2.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 5.78 %
GWO.PR.Y Insurance Straight -2.64 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 5.80 %
GWO.PR.N FixedReset Ins Non -2.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 5.68 %
IFC.PR.F Insurance Straight -1.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 22.68
Evaluated at bid price : 22.97
Bid-YTW : 5.79 %
GWO.PR.L Insurance Straight -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 23.95
Evaluated at bid price : 24.20
Bid-YTW : 5.86 %
PWF.PR.F Perpetual-Discount -1.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 22.49
Evaluated at bid price : 22.75
Bid-YTW : 5.86 %
SLF.PR.D Insurance Straight -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 5.43 %
ENB.PF.G FixedReset Disc -1.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 22.91
Evaluated at bid price : 24.10
Bid-YTW : 6.32 %
BN.PF.E FixedReset Disc 1.23 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2030-04-01
Maturity Price : 25.00
Evaluated at bid price : 24.60
Bid-YTW : 5.70 %
CU.PR.G Perpetual-Discount 1.59 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 19.82
Evaluated at bid price : 19.82
Bid-YTW : 5.74 %
ENB.PR.Y FixedReset Disc 2.88 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 22.56
Evaluated at bid price : 23.20
Bid-YTW : 6.30 %
CCS.PR.C Insurance Straight 4.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 22.24
Evaluated at bid price : 22.51
Bid-YTW : 5.57 %
IFC.PR.G FixedReset Ins Non 20.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 23.64
Evaluated at bid price : 24.00
Bid-YTW : 6.37 %
Volume Highlights
Issue Index Shares
Traded
Notes
CU.PR.C FixedReset Disc 101,361 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-06-01
Maturity Price : 25.00
Evaluated at bid price : 25.13
Bid-YTW : 4.96 %
ENB.PF.E FixedReset Disc 56,281 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 22.83
Evaluated at bid price : 23.88
Bid-YTW : 6.32 %
ENB.PR.T FixedReset Disc 33,598 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 23.28
Evaluated at bid price : 24.60
Bid-YTW : 6.21 %
BILP.PR.A FixedReset Prem 20,050 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-10-01
Maturity Price : 25.00
Evaluated at bid price : 24.98
Bid-YTW : 5.79 %
PWF.PR.G Perpetual-Premium 18,720 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2026-10-24
Maturity Price : 25.00
Evaluated at bid price : 25.30
Bid-YTW : 2.09 %
GWO.PR.Q Insurance Straight 15,961 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 22.04
Evaluated at bid price : 22.27
Bid-YTW : 5.80 %
There were 8 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
BN.PR.Z FixedReset Disc Quote: 23.50 – 25.38
Spot Rate : 1.8800
Average : 1.0872

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 23.02
Evaluated at bid price : 23.50
Bid-YTW : 6.91 %

MFC.PR.B Insurance Straight Quote: 20.74 – 21.74
Spot Rate : 1.0000
Average : 0.5946

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 20.74
Evaluated at bid price : 20.74
Bid-YTW : 5.65 %

PWF.PR.P FixedReset Disc Quote: 22.20 – 23.20
Spot Rate : 1.0000
Average : 0.6701

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 21.81
Evaluated at bid price : 22.20
Bid-YTW : 5.70 %

ENB.PR.T FixedReset Disc Quote: 24.60 – 25.39
Spot Rate : 0.7900
Average : 0.4616

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 23.28
Evaluated at bid price : 24.60
Bid-YTW : 6.21 %

FTS.PR.J Perpetual-Discount Quote: 20.80 – 21.63
Spot Rate : 0.8300
Average : 0.5329

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 20.80
Evaluated at bid price : 20.80
Bid-YTW : 5.78 %

IFC.PR.F Insurance Straight Quote: 22.97 – 24.40
Spot Rate : 1.4300
Average : 1.1753

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-24
Maturity Price : 22.68
Evaluated at bid price : 22.97
Bid-YTW : 5.79 %

Market Action

September 23, 2026

Fun day for bonds:

The world’s most influential bond yield surged decisively above 5 per cent on Wednesday as more signs emerged of growing inflationary pressures in the U.S., sending stocks and fixed income portfolios tumbling.

The benchmark U.S. 10-year yield briefly rose to near 5.14 per cent, back to where it was in 2007 before the global financial crisis caused yields to crater. In late afternoon trading, it was fetching 5.10 per cent, up 16 basis points for the session.

That was still a large daily move for the bond market, and had Canadian bond yields surging as well. The Canada five-year yield, closely followed for its impact on fixed mortgage rates and GICs, hit its highest since 2024.

Bond yields were higher across the curve – from short-term tenures to long term – an indication that traders were bracing not only for rate hikes but also for inflationary pressures to linger. That also meant investors widely suffered declines in bond portfolios – prices move inversely to yields.

All three major U.S. equity indexes weakened, with losses for Canada’s S&P/TSX Compositive Index – heavily weighted towards materials and interest-sensitive stocks that tend to weaken when yields rise – outpacing Wall Street. It closed down 584.18 points, or 1.6 per cent, marking its biggest one-day decline since June 5.
…
Adding to the hawkish tone, Fed Governor Michael Barr said that the central bank took an important step last week to “recalibrate” short-term borrowing costs to bring down inflation, and signaled ‌that further rate ​hikes will likely be needed.

Fed funds futures traders are now pricing in a 66 per cent chance of an October rate hike, up from 53 per cent a day earlier.
…
The U.S. ⁠Treasury Department also drew very weak demand for a US$70-billion 5-year note auction amid the bond market selloff, with the notes selling at the highest yield ​at an auction since 2007.
…
The Dow Jones Industrial Average fell 0.68 per cent and the S&P 500 dropped 0.75 per cent. The Nasdaq Composite was down 1.13 per cent, a sharp reversal after hitting a record high on Tuesday.

Canada five-years at 3.68%! Who’da thunk it?

PerpetualDiscounts now yield 5.80%, equivalent to 7.54% interest at the standard conversion factor of 1.3x. Long corporates yielded 5.38% on 2026-09-16. Therefore the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) has remained constant at the 215bp reported September 16.

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.6228 % 2,798.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.6228 % 5,270.2
Floater 5.16 % 5.26 % 28,579 15.12 3 0.6228 % 3,037.3
OpRet 0.00 % 0.00 % 0 0.00 0 -0.2979 % 3,628.1
SplitShare 4.66 % 4.75 % 52,388 2.51 4 -0.2979 % 4,332.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.2979 % 3,380.6
Perpetual-Premium 5.73 % 5.77 % 67,997 14.03 9 -0.3420 % 3,028.4
Perpetual-Discount 5.73 % 5.80 % 40,749 14.13 21 -0.5507 % 3,300.3
FixedReset Disc 5.63 % 6.21 % 80,800 13.54 21 -0.3766 % 3,384.7
Insurance Straight 5.65 % 5.72 % 53,883 14.31 19 -1.2620 % 3,182.7
FloatingReset 0.00 % 0.00 % 0 0.00 0 -0.3766 % 4,132.8
FixedReset Prem 5.95 % 4.55 % 74,996 2.01 27 -0.0559 % 2,650.8
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -0.3766 % 3,459.9
FixedReset Ins Non 5.28 % 5.40 % 55,101 2.52 14 -1.5233 % 3,232.6
Performance Highlights
Issue Index Change Notes
IFC.PR.G FixedReset Ins Non -22.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 19.87
Evaluated at bid price : 19.87
Bid-YTW : 7.72 %
CCS.PR.C Insurance Straight -4.57 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.85 %
SLF.PR.E Insurance Straight -3.92 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 5.63 %
ENB.PR.Y FixedReset Disc -2.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 22.15
Evaluated at bid price : 22.55
Bid-YTW : 6.49 %
CU.PR.G Perpetual-Discount -2.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 19.51
Evaluated at bid price : 19.51
Bid-YTW : 5.83 %
GWO.PR.I Insurance Straight -2.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 19.88
Evaluated at bid price : 19.88
Bid-YTW : 5.69 %
IFC.PR.E Insurance Straight -2.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 22.54
Evaluated at bid price : 22.79
Bid-YTW : 5.72 %
SLF.PR.C Insurance Straight -1.91 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 20.50
Evaluated at bid price : 20.50
Bid-YTW : 5.46 %
FTS.PR.H FixedReset Disc -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 20.76
Evaluated at bid price : 20.76
Bid-YTW : 5.86 %
IFC.PR.M Perpetual-Premium -1.60 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 24.17
Evaluated at bid price : 24.55
Bid-YTW : 5.61 %
GWO.PR.H Insurance Straight -1.50 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 21.05
Evaluated at bid price : 21.05
Bid-YTW : 5.79 %
BN.PR.M Perpetual-Discount -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 19.85
Evaluated at bid price : 19.85
Bid-YTW : 6.02 %
POW.PR.C Perpetual-Premium -1.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 24.88
Evaluated at bid price : 25.11
Bid-YTW : 5.88 %
GWO.PR.Y Insurance Straight -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 20.04
Evaluated at bid price : 20.04
Bid-YTW : 5.65 %
GWO.PR.R Insurance Straight -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 5.78 %
ENB.PR.H FixedReset Disc -1.12 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 23.43
Evaluated at bid price : 23.77
Bid-YTW : 6.08 %
GWO.PR.G Insurance Straight -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 22.49
Evaluated at bid price : 22.75
Bid-YTW : 5.73 %
BN.PF.C Perpetual-Discount -1.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 20.29
Evaluated at bid price : 20.29
Bid-YTW : 6.01 %
BN.PF.D Perpetual-Discount -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 20.49
Evaluated at bid price : 20.49
Bid-YTW : 6.02 %
ENB.PR.F FixedReset Disc -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 23.27
Evaluated at bid price : 23.66
Bid-YTW : 6.40 %
BN.PR.B Floater -1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 14.85
Evaluated at bid price : 14.85
Bid-YTW : 5.27 %
GWO.PR.N FixedReset Ins Non 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 21.04
Evaluated at bid price : 21.04
Bid-YTW : 5.56 %
BN.PR.K Floater 2.62 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 14.89
Evaluated at bid price : 14.89
Bid-YTW : 5.26 %
Volume Highlights
Issue Index Shares
Traded
Notes
IFC.PR.C FixedReset Ins Non 81,900 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2026-10-30
Maturity Price : 25.00
Evaluated at bid price : 24.98
Bid-YTW : 5.90 %
GWO.PR.N FixedReset Ins Non 52,575 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 21.04
Evaluated at bid price : 21.04
Bid-YTW : 5.56 %
ENB.PF.E FixedReset Disc 40,480 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 22.83
Evaluated at bid price : 23.88
Bid-YTW : 6.32 %
BILP.PR.A FixedReset Prem 22,000 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : 5.67 %
NA.PR.S FixedReset Prem 18,600 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-05-15
Maturity Price : 25.00
Evaluated at bid price : 26.20
Bid-YTW : 4.55 %
GWO.PR.R Insurance Straight 12,680 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 5.78 %
There were 1 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
IFC.PR.G FixedReset Ins Non Quote: 19.87 – 26.05
Spot Rate : 6.1800
Average : 3.3779

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 19.87
Evaluated at bid price : 19.87
Bid-YTW : 7.72 %

GWO.PR.R Insurance Straight Quote: 20.90 – 21.90
Spot Rate : 1.0000
Average : 0.6056

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 5.78 %

SLF.PR.E Insurance Straight Quote: 20.10 – 21.20
Spot Rate : 1.1000
Average : 0.7493

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 5.63 %

CCS.PR.C Insurance Straight Quote: 21.50 – 22.85
Spot Rate : 1.3500
Average : 1.0363

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 21.50
Evaluated at bid price : 21.50
Bid-YTW : 5.85 %

ENB.PR.Y FixedReset Disc Quote: 22.55 – 23.80
Spot Rate : 1.2500
Average : 0.9483

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 22.15
Evaluated at bid price : 22.55
Bid-YTW : 6.49 %

PWF.PR.K Perpetual-Discount Quote: 21.65 – 22.36
Spot Rate : 0.7100
Average : 0.5003

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-23
Maturity Price : 21.38
Evaluated at bid price : 21.65
Bid-YTW : 5.80 %

Market Action

September 22, 2026

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.1555 % 2,781.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.1555 % 5,237.6
Floater 5.20 % 5.22 % 28,880 15.19 3 -0.1555 % 3,018.5
OpRet 0.00 % 0.00 % 0 0.00 0 0.2488 % 3,639.0
SplitShare 4.64 % 4.39 % 52,810 2.52 4 0.2488 % 4,345.7
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2488 % 3,390.7
Perpetual-Premium 5.71 % 5.71 % 66,156 14.05 9 0.2985 % 3,038.8
Perpetual-Discount 5.70 % 5.76 % 40,468 14.17 21 0.1271 % 3,318.6
FixedReset Disc 5.61 % 6.21 % 81,611 13.55 21 0.2237 % 3,397.5
Insurance Straight 5.58 % 5.59 % 51,650 14.47 19 0.4327 % 3,223.4
FloatingReset 0.00 % 0.00 % 0 0.00 0 0.2237 % 4,148.4
FixedReset Prem 5.95 % 4.45 % 75,090 2.02 27 -0.0573 % 2,652.3
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 0.2237 % 3,472.9
FixedReset Ins Non 5.20 % 5.24 % 48,787 1.87 14 0.8016 % 3,282.6
Performance Highlights
Issue Index Change Notes
BN.PF.E FixedReset Disc 1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 23.02
Evaluated at bid price : 24.25
Bid-YTW : 6.05 %
SLF.PR.D Insurance Straight 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 20.85
Evaluated at bid price : 20.85
Bid-YTW : 5.36 %
GWO.PR.Y Insurance Straight 1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 20.28
Evaluated at bid price : 20.28
Bid-YTW : 5.58 %
PWF.PR.L Perpetual-Discount 1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 22.03
Evaluated at bid price : 22.26
Bid-YTW : 5.81 %
IFC.PR.M Perpetual-Premium 1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 24.55
Evaluated at bid price : 24.95
Bid-YTW : 5.52 %
GWO.PR.I Insurance Straight 2.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 20.35
Evaluated at bid price : 20.35
Bid-YTW : 5.56 %
MFC.PR.L FixedReset Ins Non 2.47 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-06-20
Maturity Price : 25.00
Evaluated at bid price : 25.26
Bid-YTW : 5.42 %
IFC.PR.E Insurance Straight 2.96 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 23.06
Evaluated at bid price : 23.32
Bid-YTW : 5.59 %
MFC.PR.Q FixedReset Ins Non 3.46 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 4.32 %
MFC.PR.F FixedReset Ins Non 4.27 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 21.65
Evaluated at bid price : 22.00
Bid-YTW : 5.55 %
ENB.PF.G FixedReset Disc 6.07 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 23.05
Evaluated at bid price : 24.45
Bid-YTW : 6.22 %
Volume Highlights
Issue Index Shares
Traded
Notes
IFC.PR.C FixedReset Ins Non 66,400 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2026-10-30
Maturity Price : 25.00
Evaluated at bid price : 24.98
Bid-YTW : 5.74 %
PWF.PR.P FixedReset Disc 61,000 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 21.88
Evaluated at bid price : 22.30
Bid-YTW : 5.67 %
GWO.PR.N FixedReset Ins Non 50,000 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 20.78
Evaluated at bid price : 20.78
Bid-YTW : 5.63 %
RY.PR.S FixedReset Prem 28,502 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-02-24
Maturity Price : 25.00
Evaluated at bid price : 26.61
Bid-YTW : 3.31 %
BILP.PR.A FixedReset Prem 18,000 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.16
Bid-YTW : 5.61 %
There were 0 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
SLF.PR.C Insurance Straight Quote: 20.90 – 22.00
Spot Rate : 1.1000
Average : 0.8347

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 20.90
Evaluated at bid price : 20.90
Bid-YTW : 5.35 %

ENB.PF.E FixedReset Disc Quote: 23.85 – 24.50
Spot Rate : 0.6500
Average : 0.4310

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 22.82
Evaluated at bid price : 23.85
Bid-YTW : 6.33 %

BN.PF.G FixedReset Prem Quote: 25.37 – 26.10
Spot Rate : 0.7300
Average : 0.5411

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2030-07-01
Maturity Price : 25.00
Evaluated at bid price : 25.37
Bid-YTW : 5.22 %

BN.PF.E FixedReset Disc Quote: 24.25 – 26.35
Spot Rate : 2.1000
Average : 1.9277

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 23.02
Evaluated at bid price : 24.25
Bid-YTW : 6.05 %

GWO.PR.P Insurance Straight Quote: 23.75 – 24.50
Spot Rate : 0.7500
Average : 0.5852

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 23.48
Evaluated at bid price : 23.75
Bid-YTW : 5.70 %

ENB.PF.A FixedReset Disc Quote: 24.45 – 25.00
Spot Rate : 0.5500
Average : 0.4082

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-22
Maturity Price : 23.14
Evaluated at bid price : 24.45
Bid-YTW : 6.24 %

Market Action

September 21, 2026

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -1.1633 % 2,785.6
FixedFloater 0.00 % 0.00 % 0 0.00 0 -1.1633 % 5,245.8
Floater 5.19 % 5.19 % 30,046 15.23 3 -1.1633 % 3,023.2
OpRet 0.00 % 0.00 % 0 0.00 0 0.0100 % 3,629.9
SplitShare 4.65 % 4.53 % 53,377 2.52 4 0.0100 % 4,334.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.0100 % 3,382.3
Perpetual-Premium 5.73 % 5.77 % 67,018 14.05 9 -0.0223 % 3,029.8
Perpetual-Discount 5.71 % 5.79 % 41,516 14.13 21 -0.1871 % 3,314.4
FixedReset Disc 5.62 % 6.19 % 78,977 13.57 21 0.0320 % 3,389.9
Insurance Straight 5.61 % 5.66 % 51,294 14.42 19 -0.1087 % 3,209.5
FloatingReset 0.00 % 0.00 % 0 0.00 0 0.0320 % 4,139.1
FixedReset Prem 5.95 % 4.39 % 76,245 2.02 27 0.0401 % 2,653.8
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 0.0320 % 3,465.2
FixedReset Ins Non 5.24 % 5.56 % 55,130 2.95 14 -0.5364 % 3,256.5
Performance Highlights
Issue Index Change Notes
MFC.PR.F FixedReset Ins Non -5.80 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 21.10
Evaluated at bid price : 21.10
Bid-YTW : 5.81 %
ENB.PF.G FixedReset Disc -5.42 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 22.37
Evaluated at bid price : 23.05
Bid-YTW : 6.63 %
BN.PR.K Floater -3.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 14.51
Evaluated at bid price : 14.51
Bid-YTW : 5.39 %
BN.PF.E FixedReset Disc -3.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 22.91
Evaluated at bid price : 24.00
Bid-YTW : 6.12 %
IFC.PR.E Insurance Straight -2.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 22.39
Evaluated at bid price : 22.65
Bid-YTW : 5.76 %
PWF.PR.L Perpetual-Discount -1.84 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 21.67
Evaluated at bid price : 21.92
Bid-YTW : 5.90 %
GWO.PR.S Insurance Straight -1.13 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 22.40
Evaluated at bid price : 22.66
Bid-YTW : 5.81 %
MFC.PR.Q FixedReset Ins Non -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 23.59
Evaluated at bid price : 24.84
Bid-YTW : 6.11 %
FTS.PR.H FixedReset Disc 1.19 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 21.25
Evaluated at bid price : 21.25
Bid-YTW : 5.72 %
FTS.PR.K FixedReset Disc 1.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 23.43
Evaluated at bid price : 24.86
Bid-YTW : 5.59 %
BN.PR.T FixedReset Disc 4.95 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 23.19
Evaluated at bid price : 23.95
Bid-YTW : 6.04 %
Volume Highlights
Issue Index Shares
Traded
Notes
NA.PR.G FixedReset Prem 91,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-11-16
Maturity Price : 25.00
Evaluated at bid price : 26.50
Bid-YTW : 4.47 %
BMO.PR.E FixedReset Prem 39,000 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-11-25
Maturity Price : 25.00
Evaluated at bid price : 26.75
Bid-YTW : 3.71 %
BILP.PR.A FixedReset Prem 28,400 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 5.62 %
IFC.PR.C FixedReset Ins Non 25,000 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2026-10-30
Maturity Price : 25.00
Evaluated at bid price : 24.98
Bid-YTW : 5.59 %
There were 0 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
BN.PF.E FixedReset Disc Quote: 24.00 – 26.35
Spot Rate : 2.3500
Average : 1.7388

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 22.91
Evaluated at bid price : 24.00
Bid-YTW : 6.12 %

ENB.PF.G FixedReset Disc Quote: 23.05 – 24.59
Spot Rate : 1.5400
Average : 1.0639

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 22.37
Evaluated at bid price : 23.05
Bid-YTW : 6.63 %

IFC.PR.E Insurance Straight Quote: 22.65 – 23.65
Spot Rate : 1.0000
Average : 0.5900

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 22.39
Evaluated at bid price : 22.65
Bid-YTW : 5.76 %

GWO.PR.S Insurance Straight Quote: 22.66 – 23.90
Spot Rate : 1.2400
Average : 0.8508

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 22.40
Evaluated at bid price : 22.66
Bid-YTW : 5.81 %

BN.PR.K Floater Quote: 14.51 – 15.39
Spot Rate : 0.8800
Average : 0.5451

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 14.51
Evaluated at bid price : 14.51
Bid-YTW : 5.39 %

PWF.PR.L Perpetual-Discount Quote: 21.92 – 22.76
Spot Rate : 0.8400
Average : 0.5546

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-21
Maturity Price : 21.67
Evaluated at bid price : 21.92
Bid-YTW : 5.90 %

Market Action

September 18, 2026

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.0658 % 2,818.4
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.0658 % 5,307.5
Floater 5.13 % 5.18 % 30,374 15.25 3 -0.0658 % 3,058.7
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0696 % 3,629.6
SplitShare 4.65 % 4.79 % 55,269 2.53 4 -0.0696 % 4,334.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0696 % 3,381.9
Perpetual-Premium 5.73 % 5.77 % 69,356 14.08 9 0.1651 % 3,030.5
Perpetual-Discount 5.69 % 5.77 % 41,524 14.16 21 0.2176 % 3,320.6
FixedReset Disc 5.62 % 6.27 % 79,890 13.48 21 0.5181 % 3,388.8
Insurance Straight 5.60 % 5.64 % 52,075 14.44 19 0.2344 % 3,213.0
FloatingReset 0.00 % 0.00 % 0 0.00 0 0.5181 % 4,137.8
FixedReset Prem 5.95 % 4.36 % 75,974 2.03 27 0.0631 % 2,652.7
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 0.5181 % 3,464.1
FixedReset Ins Non 5.21 % 5.39 % 49,609 1.88 14 0.3796 % 3,274.0
Performance Highlights
Issue Index Change Notes
ENB.PF.C FixedReset Disc -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-18
Maturity Price : 22.87
Evaluated at bid price : 23.90
Bid-YTW : 6.38 %
GWO.PR.G Insurance Straight 1.02 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-18
Maturity Price : 22.63
Evaluated at bid price : 22.88
Bid-YTW : 5.70 %
BIP.PR.E FixedReset Prem 1.36 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-03-31
Maturity Price : 25.00
Evaluated at bid price : 26.00
Bid-YTW : 3.81 %
GWO.PR.R Insurance Straight 1.63 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-18
Maturity Price : 21.17
Evaluated at bid price : 21.17
Bid-YTW : 5.70 %
ENB.PF.G FixedReset Disc 5.73 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-18
Maturity Price : 23.02
Evaluated at bid price : 24.37
Bid-YTW : 6.29 %
MFC.PR.F FixedReset Ins Non 6.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-18
Maturity Price : 21.92
Evaluated at bid price : 22.40
Bid-YTW : 5.50 %
BN.PR.Z FixedReset Disc 7.87 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.35
Bid-YTW : 4.82 %
Volume Highlights
Issue Index Shares
Traded
Notes
IFC.PR.C FixedReset Ins Non 449,300 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2026-10-30
Maturity Price : 25.00
Evaluated at bid price : 24.98
Bid-YTW : 5.24 %
BILP.PR.A FixedReset Prem 18,811 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.15
Bid-YTW : 5.61 %
GWO.PF.A Perpetual-Premium 16,550 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-18
Maturity Price : 24.55
Evaluated at bid price : 24.95
Bid-YTW : 5.72 %
PWF.PR.P FixedReset Disc 14,400 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-18
Maturity Price : 21.86
Evaluated at bid price : 22.27
Bid-YTW : 5.73 %
ENB.PR.P FixedReset Disc 10,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-18
Maturity Price : 23.19
Evaluated at bid price : 24.26
Bid-YTW : 6.29 %
There were 0 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
SLF.PR.C Insurance Straight Quote: 20.84 – 22.25
Spot Rate : 1.4100
Average : 0.7890

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-18
Maturity Price : 20.84
Evaluated at bid price : 20.84
Bid-YTW : 5.36 %

BN.PF.E FixedReset Disc Quote: 24.80 – 26.35
Spot Rate : 1.5500
Average : 1.0686

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2030-04-01
Maturity Price : 25.00
Evaluated at bid price : 24.80
Bid-YTW : 5.42 %

PWF.PR.P FixedReset Disc Quote: 22.27 – 23.20
Spot Rate : 0.9300
Average : 0.5779

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-18
Maturity Price : 21.86
Evaluated at bid price : 22.27
Bid-YTW : 5.73 %

GWO.PR.M Insurance Straight Quote: 25.16 – 25.96
Spot Rate : 0.8000
Average : 0.4905

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2026-10-18
Maturity Price : 25.00
Evaluated at bid price : 25.16
Bid-YTW : -4.25 %

ENB.PF.K FixedReset Prem Quote: 25.75 – 26.45
Spot Rate : 0.7000
Average : 0.4487

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-03-01
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 4.31 %

GWO.PR.P Insurance Straight Quote: 23.75 – 24.55
Spot Rate : 0.8000
Average : 0.5959

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-18
Maturity Price : 23.48
Evaluated at bid price : 23.75
Bid-YTW : 5.70 %

Market Action

September 17, 2026

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.9298 % 2,820.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.9298 % 5,311.0
Floater 5.12 % 5.18 % 30,723 15.25 3 0.9298 % 3,060.8
OpRet 0.00 % 0.00 % 0 0.00 0 -0.0099 % 3,632.1
SplitShare 4.65 % 4.76 % 55,532 2.53 4 -0.0099 % 4,337.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.0099 % 3,384.3
Perpetual-Premium 5.74 % 5.82 % 72,083 14.05 9 0.2236 % 3,025.5
Perpetual-Discount 5.71 % 5.79 % 42,124 14.13 21 0.2527 % 3,313.4
FixedReset Disc 5.65 % 6.28 % 81,205 13.48 21 -0.4100 % 3,371.4
Insurance Straight 5.61 % 5.63 % 49,563 14.47 19 0.6410 % 3,205.5
FloatingReset 0.00 % 0.00 % 0 0.00 0 -0.4100 % 4,116.5
FixedReset Prem 5.95 % 4.59 % 79,086 2.03 27 0.0818 % 2,651.1
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -0.4100 % 3,446.2
FixedReset Ins Non 5.23 % 5.49 % 55,578 1.88 14 0.1532 % 3,261.7
Performance Highlights
Issue Index Change Notes
BN.PR.Z FixedReset Disc -8.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 23.02
Evaluated at bid price : 23.50
Bid-YTW : 6.97 %
ENB.PF.G FixedReset Disc -4.79 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 22.37
Evaluated at bid price : 23.05
Bid-YTW : 6.68 %
BN.PF.M FixedReset Prem -1.37 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-01-01
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 5.37 %
ENB.PR.D FixedReset Disc 1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 23.31
Evaluated at bid price : 23.75
Bid-YTW : 6.29 %
SLF.PR.C Insurance Straight 1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 20.83
Evaluated at bid price : 20.83
Bid-YTW : 5.36 %
ENB.PF.A FixedReset Disc 1.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 23.13
Evaluated at bid price : 24.43
Bid-YTW : 6.30 %
GWO.PR.Q Insurance Straight 1.49 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 22.26
Evaluated at bid price : 22.53
Bid-YTW : 5.73 %
BN.PR.B Floater 3.58 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 15.05
Evaluated at bid price : 15.05
Bid-YTW : 5.20 %
MFC.PR.B Insurance Straight 3.93 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 21.44
Evaluated at bid price : 21.70
Bid-YTW : 5.37 %
GWO.PR.Y Insurance Straight 5.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 20.05
Evaluated at bid price : 20.05
Bid-YTW : 5.64 %
Volume Highlights
Issue Index Shares
Traded
Notes
ENB.PR.Y FixedReset Disc 11,371 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 22.56
Evaluated at bid price : 23.20
Bid-YTW : 6.35 %
BILP.PR.A FixedReset Prem 10,400 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.21
Bid-YTW : 5.55 %
There were 0 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
ENB.PF.G FixedReset Disc Quote: 23.05 – 24.56
Spot Rate : 1.5100
Average : 0.9498

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 22.37
Evaluated at bid price : 23.05
Bid-YTW : 6.68 %

GWO.PR.R Insurance Straight Quote: 20.83 – 21.95
Spot Rate : 1.1200
Average : 0.7981

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 20.83
Evaluated at bid price : 20.83
Bid-YTW : 5.79 %

ENB.PR.F FixedReset Disc Quote: 23.96 – 24.69
Spot Rate : 0.7300
Average : 0.4558

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 23.59
Evaluated at bid price : 23.96
Bid-YTW : 6.37 %

GWO.PR.H Insurance Straight Quote: 21.15 – 22.51
Spot Rate : 1.3600
Average : 1.0946

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 21.15
Evaluated at bid price : 21.15
Bid-YTW : 5.76 %

BN.PR.Z FixedReset Disc Quote: 23.50 – 25.55
Spot Rate : 2.0500
Average : 1.7909

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 23.02
Evaluated at bid price : 23.50
Bid-YTW : 6.97 %

GWO.PR.L Insurance Straight Quote: 24.41 – 25.00
Spot Rate : 0.5900
Average : 0.3489

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-17
Maturity Price : 24.16
Evaluated at bid price : 24.41
Bid-YTW : 5.80 %

Market Action

September 16, 2026

The FOMC tightened today:

The Federal Open Market Committee approved the following statement for release by a 12 – 0 vote:

The Committee decided to raise the target range for the federal funds rate by 1/4 percentage point to 3-3/4 to 4 percent, in support of the Federal Reserve’s dual mandate. The Committee is continuing its policy of maintaining ample reserves in the banking system.

Economic activity is expanding at a solid pace. While uncertainty remains elevated owing, in part, to geopolitical developments, domestic spending has been resilient. Productivity growth is strong, and capital investment is robust. Job gains have kept pace with the workforce, and the unemployment rate has changed little.

Inflation remains elevated. Today’s policy action will support a timelier return to the Committee’s 2 percent goal. The Committee will deliver price stability.

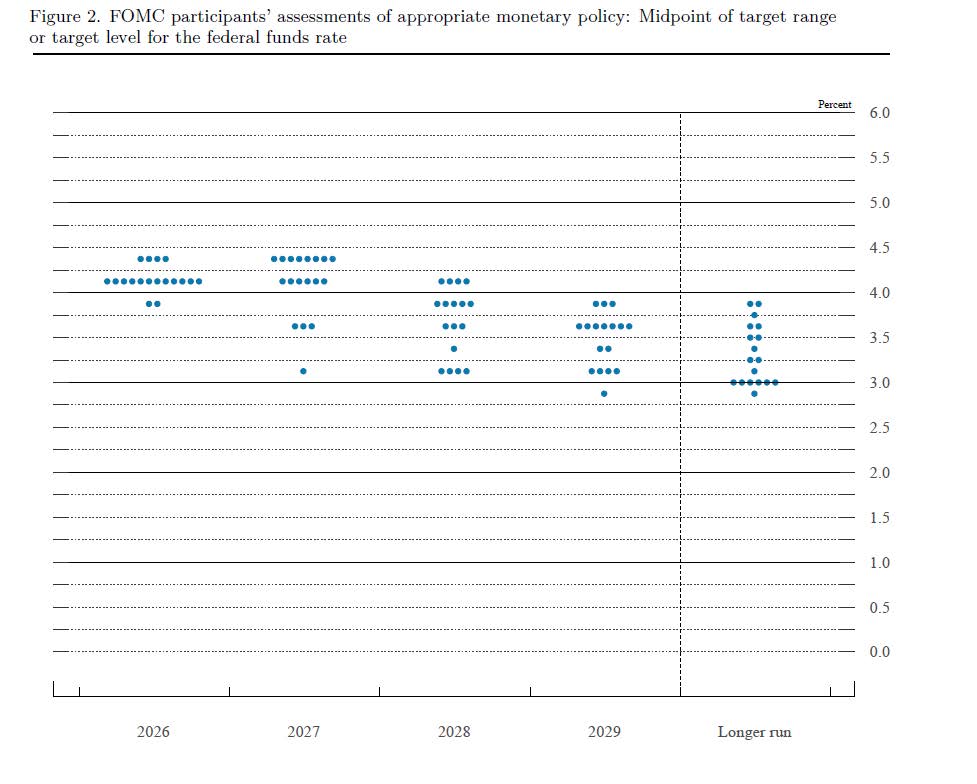
… and the dot plot suggests there will be more to come … and not just for a little while:

Equities didn’t like it:

Before the Fed’s announcement, the three major U.S. stock indexes had ‌been gaining ground, ​with a chips rebound, giving the tech-heavy Nasdaq ‌the edge. Earlier in the session, robust U.S. retail sales data suggested consumers were still spending, despite an affordability squeeze due to rising ​prices, particularly at the gasoline pump.

The war in the Middle East expanded ⁠as Saudi warplanes pounded Yemen while Iran-backed Houthi fighters launched drones and missiles at Saudi cities in a signal ⁠of Iran’s extended reach in the widening conflict.

Even so, oil prices dipped after reports that Saudi Arabia was offering additional crude cargoes via Oman eased concerns about supply ​disruptions. Crude is up over 20% in the last 2-1/2 weeks. Front-month WTI settled down 3.2% and Brent crude settled down 2.7%.

The Dow Jones Industrial Average fell 631.33 points, or 1.21%, to 51,461.78, the S&P 500 lost 33.59 points, or 0.44%, to 7,552.14 and the Nasdaq Composite lost 3.15 points, or 0.01%, to 25,978.43.

The S&P/TSX Composite Index ended down 90.8 points, or ⁠0.3%, ​at 35,491.27, its lowest closing level since July 31.
…
Six of the 10 major TSX sectors notched gains, led by a 1.9% advance ⁠for utilities as yields on ​long-dated bonds eased. Short-term U.S. bond yields, however, did rise following the Fed announcement and press conference, signaling a market pricing in more rate hikes ahead. Fed policy decisions having a greater immediate impact on the shorter end of the bond curve.

PerpetualDiscounts now yield 5.82%, equivalent to 7.57% interest at the standard conversion factor of 1.3x. Long corporates yielded 5.41% on 2026-09-16. Therefore the pre-tax interest-equivalent spread (in this context, the “Seniority Spread”) has widened to 215bp from the 200bp reported September 9 .

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.0221 % 2,794.3
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.0221 % 5,262.1
Floater 5.17 % 5.20 % 31,084 15.23 3 0.0221 % 3,032.6
OpRet 0.00 % 0.00 % 0 0.00 0 0.1494 % 3,632.5
SplitShare 4.65 % 4.41 % 55,993 2.53 4 0.1494 % 4,337.9
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.1494 % 3,384.6
Perpetual-Premium 5.75 % 5.83 % 75,010 14.03 9 -0.0715 % 3,018.7
Perpetual-Discount 5.72 % 5.82 % 42,482 14.12 21 0.0843 % 3,305.0
FixedReset Disc 5.63 % 6.28 % 84,664 13.43 21 -0.2115 % 3,385.3
Insurance Straight 5.65 % 5.65 % 49,519 14.37 19 -0.4814 % 3,185.0
FloatingReset 0.00 % 0.00 % 0 0.00 0 -0.2115 % 4,133.4
FixedReset Prem 5.96 % 4.66 % 82,110 2.03 27 -0.1404 % 2,648.9
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -0.2115 % 3,460.4
FixedReset Ins Non 5.24 % 5.50 % 55,349 1.88 14 -0.5306 % 3,256.7
Performance Highlights
Issue Index Change Notes
GWO.PR.Y Insurance Straight -5.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.95 %
BN.PR.T FixedReset Disc -5.39 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 22.14
Evaluated at bid price : 22.80
Bid-YTW : 6.42 %
MFC.PR.L FixedReset Ins Non -3.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 23.29
Evaluated at bid price : 24.65
Bid-YTW : 5.83 %
BN.PR.B Floater -2.48 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 14.53
Evaluated at bid price : 14.53
Bid-YTW : 5.38 %
MFC.PR.Q FixedReset Ins Non -2.26 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.12
Bid-YTW : 5.67 %
BN.PR.M Perpetual-Discount -2.22 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 20.24
Evaluated at bid price : 20.24
Bid-YTW : 5.89 %
GWO.PR.Q Insurance Straight -1.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 21.97
Evaluated at bid price : 22.20
Bid-YTW : 5.81 %
ENB.PR.D FixedReset Disc -1.47 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 23.06
Evaluated at bid price : 23.50
Bid-YTW : 6.36 %
GWO.PR.N FixedReset Ins Non -1.44 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 5.73 %
NA.PR.G FixedReset Prem -1.31 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-11-16
Maturity Price : 25.00
Evaluated at bid price : 26.40
Bid-YTW : 4.63 %
ENB.PR.Y FixedReset Disc -1.29 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 22.44
Evaluated at bid price : 23.00
Bid-YTW : 6.41 %
SLF.PR.C Insurance Straight -1.25 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 20.59
Evaluated at bid price : 20.59
Bid-YTW : 5.43 %
GWO.PR.G Insurance Straight -1.17 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 22.49
Evaluated at bid price : 22.75
Bid-YTW : 5.73 %
BN.PF.B FixedReset Prem -1.10 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-04-01
Maturity Price : 25.00
Evaluated at bid price : 25.22
Bid-YTW : 5.71 %
SLF.PR.D Insurance Straight -1.06 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 20.48
Evaluated at bid price : 20.48
Bid-YTW : 5.46 %
PWF.PF.A Perpetual-Discount -1.05 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 19.76
Evaluated at bid price : 19.76
Bid-YTW : 5.78 %
GWO.PR.I Insurance Straight -1.04 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 5.65 %
BN.PF.A FixedReset Prem 1.17 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-09-30
Maturity Price : 25.00
Evaluated at bid price : 25.85
Bid-YTW : 4.88 %
BN.PR.K Floater 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 15.04
Evaluated at bid price : 15.04
Bid-YTW : 5.20 %
PWF.PR.A Floater 1.30 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 15.60
Evaluated at bid price : 15.60
Bid-YTW : 5.05 %
BN.PF.M FixedReset Prem 1.39 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-01-01
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 5.00 %
GWO.PR.S Insurance Straight 2.69 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 22.66
Evaluated at bid price : 22.90
Bid-YTW : 5.74 %
GWO.PR.R Insurance Straight 2.90 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 20.95
Evaluated at bid price : 20.95
Bid-YTW : 5.75 %
CU.PR.J Perpetual-Discount 6.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 20.91
Evaluated at bid price : 20.91
Bid-YTW : 5.74 %
BN.PR.Z FixedReset Disc 8.94 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2027-12-31
Maturity Price : 25.00
Evaluated at bid price : 25.60
Bid-YTW : 4.00 %
Volume Highlights
Issue Index Shares
Traded
Notes
ENB.PR.B FixedReset Disc 34,140 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 23.08
Evaluated at bid price : 23.75
Bid-YTW : 6.33 %
FTS.PR.M FixedReset Prem 28,000 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-12-01
Maturity Price : 25.00
Evaluated at bid price : 25.10
Bid-YTW : 5.47 %
BILP.PR.A FixedReset Prem 26,975 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.20
Bid-YTW : 5.55 %
GWO.PF.A Perpetual-Premium 17,505 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 24.45
Evaluated at bid price : 24.84
Bid-YTW : 5.74 %
SLF.PR.D Insurance Straight 10,925 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 20.48
Evaluated at bid price : 20.48
Bid-YTW : 5.46 %
GWO.PR.R Insurance Straight 10,500 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 20.95
Evaluated at bid price : 20.95
Bid-YTW : 5.75 %
There were 0 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
GWO.PR.Y Insurance Straight Quote: 19.00 – 20.50
Spot Rate : 1.5000
Average : 1.0009

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 19.00
Evaluated at bid price : 19.00
Bid-YTW : 5.95 %

BN.PR.T FixedReset Disc Quote: 22.80 – 24.20
Spot Rate : 1.4000
Average : 0.9151

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 22.14
Evaluated at bid price : 22.80
Bid-YTW : 6.42 %

MFC.PR.L FixedReset Ins Non Quote: 24.65 – 25.65
Spot Rate : 1.0000
Average : 0.6614

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 23.29
Evaluated at bid price : 24.65
Bid-YTW : 5.83 %

ENB.PF.E FixedReset Disc Quote: 23.91 – 24.50
Spot Rate : 0.5900
Average : 0.3485

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 22.84
Evaluated at bid price : 23.91
Bid-YTW : 6.36 %

MFC.PR.B Insurance Straight Quote: 20.88 – 21.88
Spot Rate : 1.0000
Average : 0.7685

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-16
Maturity Price : 20.88
Evaluated at bid price : 20.88
Bid-YTW : 5.60 %

NA.PR.G FixedReset Prem Quote: 26.40 – 27.28
Spot Rate : 0.8800
Average : 0.6651

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-11-16
Maturity Price : 25.00
Evaluated at bid price : 26.40
Bid-YTW : 4.63 %

Market Action

September 15, 2026

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 -0.3311 % 2,793.7
FixedFloater 0.00 % 0.00 % 0 0.00 0 -0.3311 % 5,260.9
Floater 5.17 % 5.25 % 32,126 15.15 3 -0.3311 % 3,031.9
OpRet 0.00 % 0.00 % 0 0.00 0 -0.1194 % 3,627.0
SplitShare 4.66 % 4.53 % 57,888 2.53 4 -0.1194 % 4,331.5
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 -0.1194 % 3,379.6
Perpetual-Premium 5.75 % 5.82 % 77,472 14.06 9 -0.2763 % 3,020.9
Perpetual-Discount 5.73 % 5.83 % 42,487 14.09 21 -0.6529 % 3,302.2
FixedReset Disc 5.61 % 6.22 % 88,117 13.56 21 0.5256 % 3,392.4
Insurance Straight 5.62 % 5.61 % 47,261 14.52 19 -0.8045 % 3,200.5
FloatingReset 0.00 % 0.00 % 0 0.00 0 0.5256 % 4,142.2
FixedReset Prem 5.95 % 4.42 % 85,042 2.04 27 -0.3669 % 2,652.6
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 0.5256 % 3,467.7
FixedReset Ins Non 5.21 % 5.00 % 55,237 1.89 14 -0.3709 % 3,274.0
Performance Highlights
Issue Index Change Notes
CU.PR.J Perpetual-Discount -6.77 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 19.70
Evaluated at bid price : 19.70
Bid-YTW : 6.09 %
GWO.PR.S Insurance Straight -4.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 22.07
Evaluated at bid price : 22.30
Bid-YTW : 5.90 %
GWO.PR.R Insurance Straight -3.55 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 20.36
Evaluated at bid price : 20.36
Bid-YTW : 5.92 %
MFC.PR.B Insurance Straight -3.45 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.57 %
BN.PR.N Perpetual-Discount -2.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 20.30
Evaluated at bid price : 20.30
Bid-YTW : 5.88 %
ENB.PF.G FixedReset Disc -1.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 22.95
Evaluated at bid price : 24.21
Bid-YTW : 6.33 %
GWO.PR.Q Insurance Straight -1.53 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 22.28
Evaluated at bid price : 22.55
Bid-YTW : 5.72 %
MFC.PR.K FixedReset Ins Non -1.34 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-09-19
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 4.77 %
CU.PR.K Perpetual-Premium -1.20 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 24.31
Evaluated at bid price : 24.70
Bid-YTW : 5.70 %
ENB.PF.A FixedReset Disc -1.18 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 23.07
Evaluated at bid price : 24.29
Bid-YTW : 6.34 %
FTS.PR.J Perpetual-Discount -1.16 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 21.35
Evaluated at bid price : 21.35
Bid-YTW : 5.62 %
PWF.PR.P FixedReset Disc -1.11 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 21.85
Evaluated at bid price : 22.27
Bid-YTW : 5.73 %
FTS.PR.K FixedReset Disc -1.09 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 23.33
Evaluated at bid price : 24.60
Bid-YTW : 5.72 %
BN.PF.M FixedReset Prem -1.02 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-01-01
Maturity Price : 25.00
Evaluated at bid price : 25.25
Bid-YTW : 5.36 %
BN.PF.E FixedReset Disc 1.30 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2030-04-01
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 5.15 %
BN.PR.X FixedReset Disc 1.31 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 21.65
Evaluated at bid price : 22.05
Bid-YTW : 6.10 %
ENB.PR.F FixedReset Disc 1.87 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 23.58
Evaluated at bid price : 23.95
Bid-YTW : 6.37 %
BN.PR.K Floater 2.34 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 14.86
Evaluated at bid price : 14.86
Bid-YTW : 5.26 %
SLF.PR.E Insurance Straight 3.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 20.75
Evaluated at bid price : 20.75
Bid-YTW : 5.44 %
CU.PR.G Perpetual-Discount 4.75 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 20.06
Evaluated at bid price : 20.06
Bid-YTW : 5.66 %
BN.PR.Z FixedReset Disc 19.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 23.02
Evaluated at bid price : 23.50
Bid-YTW : 6.97 %
Volume Highlights
Issue Index Shares
Traded
Notes
IFC.PR.C FixedReset Ins Non 554,800 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2026-10-30
Maturity Price : 25.00
Evaluated at bid price : 24.96
Bid-YTW : 5.55 %
NA.PR.E FixedReset Prem 211,602 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-05-15
Maturity Price : 25.00
Evaluated at bid price : 25.72
Bid-YTW : 4.35 %
BN.PF.F FixedReset Prem 120,160 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.49
Bid-YTW : 5.08 %
BN.PR.Z FixedReset Disc 102,200 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 23.02
Evaluated at bid price : 23.50
Bid-YTW : 6.97 %
ENB.PF.A FixedReset Disc 74,900 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 23.07
Evaluated at bid price : 24.29
Bid-YTW : 6.34 %
IFC.PR.G FixedReset Ins Non 59,000 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-06-30
Maturity Price : 25.00
Evaluated at bid price : 25.55
Bid-YTW : 4.61 %
There were 10 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
MFC.PR.B Insurance Straight Quote: 21.00 – 21.84
Spot Rate : 0.8400
Average : 0.5146

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 21.00
Evaluated at bid price : 21.00
Bid-YTW : 5.57 %

CU.PR.J Perpetual-Discount Quote: 19.70 – 21.39
Spot Rate : 1.6900
Average : 1.3662

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 19.70
Evaluated at bid price : 19.70
Bid-YTW : 6.09 %

IFC.PR.F Insurance Straight Quote: 23.65 – 24.40
Spot Rate : 0.7500
Average : 0.5054

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 23.36
Evaluated at bid price : 23.65
Bid-YTW : 5.61 %

GWO.PR.H Insurance Straight Quote: 21.20 – 22.51
Spot Rate : 1.3100
Average : 1.0816

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 5.74 %

GWO.PR.R Insurance Straight Quote: 20.36 – 21.36
Spot Rate : 1.0000
Average : 0.7908

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 20.36
Evaluated at bid price : 20.36
Bid-YTW : 5.92 %

BN.PR.R FixedReset Disc Quote: 24.11 – 24.70
Spot Rate : 0.5900
Average : 0.3827

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-15
Maturity Price : 22.84
Evaluated at bid price : 24.11
Bid-YTW : 5.95 %

Market Action

September 14, 2026

HIMIPref™ Preferred Indices
These values reflect the December 2008 revision of the HIMIPref™ Indices

Values are provisional and are finalized monthly
Index Mean
Current
Yield
(at bid)
Median
YTW
Median
Average
Trading
Value
Median
Mod Dur
(YTW)
Issues Day’s Perf. Index Value
Ratchet 0.00 % 0.00 % 0 0.00 0 0.4656 % 2,803.0
FixedFloater 0.00 % 0.00 % 0 0.00 0 0.4656 % 5,278.4
Floater 5.16 % 5.23 % 32,381 15.04 3 0.4656 % 3,042.0
OpRet 0.00 % 0.00 % 0 0.00 0 0.2194 % 3,631.4
SplitShare 4.65 % 4.17 % 57,029 2.54 4 0.2194 % 4,336.6
Interest-Bearing 0.00 % 0.00 % 0 0.00 0 0.2194 % 3,383.6
Perpetual-Premium 5.73 % 5.84 % 72,361 14.03 9 -0.0979 % 3,029.2
Perpetual-Discount 5.69 % 5.80 % 42,896 14.13 21 -0.3169 % 3,323.9
FixedReset Disc 5.64 % 6.21 % 85,527 13.54 21 -1.1521 % 3,374.7
Insurance Straight 5.58 % 5.61 % 47,961 14.45 19 -0.6776 % 3,226.4
FloatingReset 0.00 % 0.00 % 0 0.00 0 -1.1521 % 4,120.5
FixedReset Prem 5.93 % 4.52 % 78,889 2.04 27 -0.1539 % 2,662.4
FixedReset Bank Non 0.00 % 0.00 % 0 0.00 0 -1.1521 % 3,449.6
FixedReset Ins Non 5.19 % 4.99 % 51,142 2.55 14 -0.3086 % 3,286.2
Performance Highlights
Issue Index Change Notes
BN.PR.Z FixedReset Disc -22.03 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 8.39 %
MFC.PR.F FixedReset Ins Non -6.40 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 5.83 %
CU.PR.G Perpetual-Discount -5.67 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 5.93 %
SLF.PR.E Insurance Straight -4.65 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 5.62 %
PWF.PR.Z Perpetual-Discount -2.70 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 21.75
Evaluated at bid price : 22.00
Bid-YTW : 5.93 %
SLF.PR.D Insurance Straight -2.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 20.60
Evaluated at bid price : 20.60
Bid-YTW : 5.42 %
NA.PR.K FixedReset Prem -1.92 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-05-01
Maturity Price : 25.00
Evaluated at bid price : 28.15
Bid-YTW : 3.03 %
GWO.PR.P Insurance Straight -1.66 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 23.41
Evaluated at bid price : 23.70
Bid-YTW : 5.70 %
SLF.PR.C Insurance Straight -1.61 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 20.77
Evaluated at bid price : 20.77
Bid-YTW : 5.38 %
GWO.PF.A Perpetual-Premium -1.36 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 24.27
Evaluated at bid price : 24.65
Bid-YTW : 5.79 %
FTS.PR.F Perpetual-Discount -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 22.12
Evaluated at bid price : 22.40
Bid-YTW : 5.50 %
PWF.PF.A Perpetual-Discount -1.23 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 20.10
Evaluated at bid price : 20.10
Bid-YTW : 5.68 %
BN.PR.K Floater -1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 14.71
Evaluated at bid price : 14.71
Bid-YTW : 5.40 %
MFC.PR.B Insurance Straight -1.14 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 21.49
Evaluated at bid price : 21.75
Bid-YTW : 5.36 %
ENB.PR.T FixedReset Disc -1.01 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 23.28
Evaluated at bid price : 24.60
Bid-YTW : 6.26 %
GWO.PR.Y Insurance Straight 1.00 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 20.20
Evaluated at bid price : 20.20
Bid-YTW : 5.59 %
GWO.PR.N FixedReset Ins Non 1.21 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 20.85
Evaluated at bid price : 20.85
Bid-YTW : 5.66 %
PWF.PR.P FixedReset Disc 1.35 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 22.02
Evaluated at bid price : 22.52
Bid-YTW : 5.66 %
MFC.PR.Q FixedReset Ins Non 1.50 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-06-19
Maturity Price : 25.00
Evaluated at bid price : 25.70
Bid-YTW : 4.26 %
BN.PF.D Perpetual-Discount 1.71 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 21.46
Evaluated at bid price : 21.46
Bid-YTW : 5.83 %
PWF.PR.A Floater 2.33 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 15.40
Evaluated at bid price : 15.40
Bid-YTW : 5.12 %
BN.PF.E FixedReset Disc 3.73 % YTW SCENARIO
Maturity Type : Call
Maturity Date : 2030-04-01
Maturity Price : 25.00
Evaluated at bid price : 25.00
Bid-YTW : 5.55 %
CU.PR.J Perpetual-Discount 7.26 % YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 21.13
Evaluated at bid price : 21.13
Bid-YTW : 5.67 %
Volume Highlights
Issue Index Shares
Traded
Notes
IFC.PR.C FixedReset Ins Non 233,000 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 24.31
Evaluated at bid price : 25.13
Bid-YTW : 6.30 %
GWO.PR.N FixedReset Ins Non 51,300 YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 20.85
Evaluated at bid price : 20.85
Bid-YTW : 5.66 %
BN.PF.B FixedReset Prem 51,100 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-04-01
Maturity Price : 25.00
Evaluated at bid price : 25.77
Bid-YTW : 5.41 %
BILP.PR.A FixedReset Prem 47,300 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2031-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.24
Bid-YTW : 5.51 %
BN.PF.G FixedReset Prem 41,000 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2030-07-01
Maturity Price : 25.00
Evaluated at bid price : 25.51
Bid-YTW : 5.44 %
BN.PF.F FixedReset Prem 32,200 YTW SCENARIO
Maturity Type : Call
Maturity Date : 2029-10-01
Maturity Price : 25.00
Evaluated at bid price : 25.75
Bid-YTW : 5.22 %
There were 4 other index-included issues trading in excess of 10,000 shares.
Wide Spread Highlights
See TMX DataLinx: ‘Last’ != ‘Close’ and the posts linked therein for an idea of why these quotes are so horrible.
Issue Index Quote Data and Yield Notes
BN.PR.Z FixedReset Disc Quote: 20.00 – 26.05
Spot Rate : 6.0500
Average : 3.8489

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 20.00
Evaluated at bid price : 20.00
Bid-YTW : 8.39 %

CM.PR.S FixedReset Prem Quote: 25.90 – 26.90
Spot Rate : 1.0000
Average : 0.5668

YTW SCENARIO
Maturity Type : Call
Maturity Date : 2028-01-31
Maturity Price : 25.00
Evaluated at bid price : 25.90
Bid-YTW : 3.74 %

CU.PR.G Perpetual-Discount Quote: 19.15 – 20.33
Spot Rate : 1.1800
Average : 0.7614

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 19.15
Evaluated at bid price : 19.15
Bid-YTW : 5.93 %

MFC.PR.F FixedReset Ins Non Quote: 21.20 – 22.86
Spot Rate : 1.6600
Average : 1.2710

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 21.20
Evaluated at bid price : 21.20
Bid-YTW : 5.83 %

GWO.PR.R Insurance Straight Quote: 21.11 – 21.95
Spot Rate : 0.8400
Average : 0.5615

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 21.11
Evaluated at bid price : 21.11
Bid-YTW : 5.71 %

GWO.PR.P Insurance Straight Quote: 23.70 – 24.60
Spot Rate : 0.9000
Average : 0.6617

YTW SCENARIO
Maturity Type : Limit Maturity
Maturity Date : 2056-09-14
Maturity Price : 23.41
Evaluated at bid price : 23.70
Bid-YTW : 5.70 %